DTA&DTL Understanding Deferred Tax
Written by the team at Prompt Plus Accounting · About us ·
why companies need to recognize Deferred Tax Assets (DTA) and Deferred Tax Liabilities (DTL) even though no actual tax payment or refund has occurred yet?
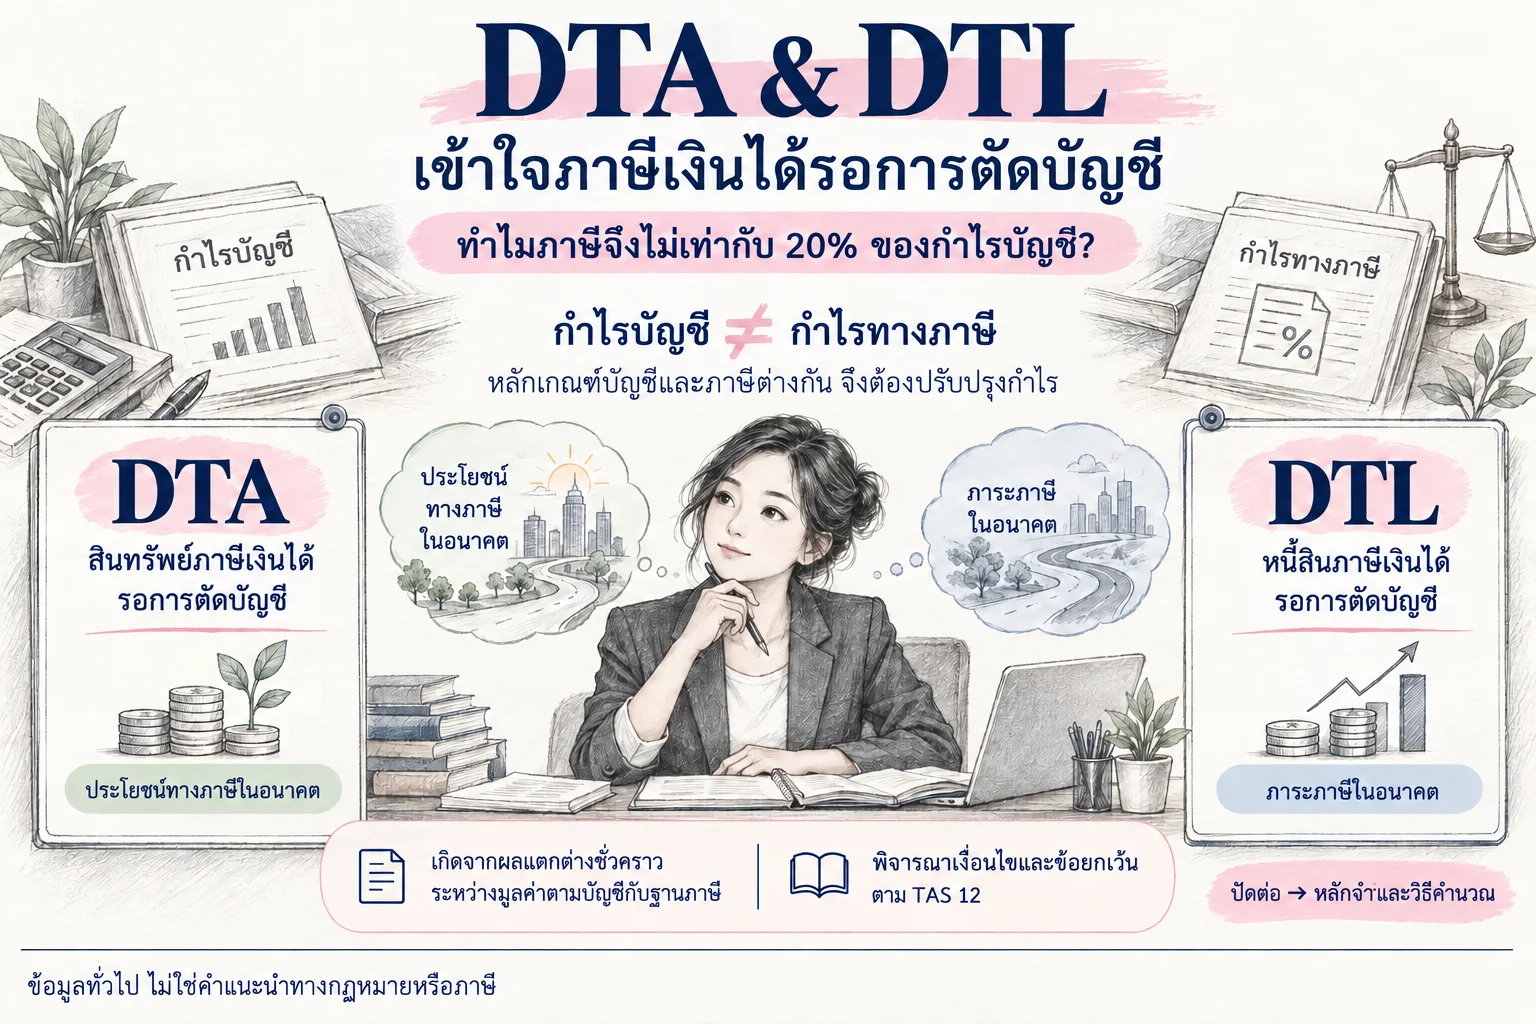
Today, we will walk you through Deferred Tax Assets (DTA) and Deferred Tax Liabilities (DTL), covering the basic concepts, calculation methods, and practical examples of asset impairment where accounting and tax depreciation periods differ.
What Are DTA and DTL?
Deferred Tax Assets (DTA) and Deferred Tax Liabilities (DTL) arise because accounting standards and tax regulations may apply different rules for recognizing income and expenses. These differences can result in discrepancies between the Carrying Amount and the Tax Base of assets or liabilities.
Under TAS 12 – Income Taxes, such differences may give rise to deferred income tax.
1.1) DTA (Deferred Tax Asset)
A Deferred Tax Asset represents a future tax benefit that a company expects to receive.
For example, a company may recognize an expense for accounting purposes in the current year, while tax regulations do not yet allow the expense to be deducted. If the expense becomes tax-deductible in a future period, it may reduce the company's future taxable income and tax payments.
*A DTA can only be recognized to the extent that it is probable that sufficient future taxable profits will be available against which the deductible temporary differences can be utilized.
1.2) DTL (Deferred Tax Liability)
A Deferred Tax Liability represents income tax that a company is expected to pay in future periods due to temporary differences between accounting and tax treatments.
For example, tax depreciation may be higher than accounting depreciation during the early years of an asset's useful life. This reduces current taxable income but may result in higher tax payments in future periods when the temporary difference reverses.
Quick and Easy Way to Remember:
Start by asking: When the temporary difference reverses in the future, will the company pay less tax or more tax?
Less tax in the future → DTA (Asset)
More tax in the future → DTL (Liability)
For assets, the general comparison is:
Carrying Amount < Tax Base → DTA
Carrying Amount > Tax Base → DTL
For liabilities, the general relationship is reversed.
*These principles apply to temporary differences that meet the recognition requirements under TAS 12 and are not subject to the exceptions specified in the standard.
Example of Recognizing a Deferred Tax Asset (DTA)
Company A has trade receivables of THB 1,000,000 and recognizes Expected Credit Losses (ECL) of THB 100,000.
For accounting purposes, the company recognizes an ECL expense of THB 100,000.
However, for tax purposes, the expense is not yet deductible because it does not meet the conditions for a bad debt write-off under applicable tax regulations.
Assume that the amount will become tax-deductible in the future and that the company will have sufficient taxable profits.
- Net carrying amount of trade receivables 900,000 THB
- Tax base of trade receivables 1,000,000 THB
Deductible temporary difference 100,000 THB
Deferred Tax Asset (DTA) 100,000 x 20% = 20,000 THB
Journal Entry
Dr. DTA 20,000 THB
Cr. Deferred Tax income 20,000 THB
Conclusion: Company A recognizes a Deferred Tax Asset of THB 20,000 because it expects to receive a future tax benefit when the deductible temporary difference reverses.
Example of Recognizing a Deferred Tax Liability (DTL)
Company B purchases machinery for THB 1,000,000.
The following assumptions apply:
Accounting treatment: Useful life 10 years Annual depreciation THB 100,000.
Tax treatment: Annual tax depreciation: THB 200,000, assuming this deduction is permitted under applicable tax regulations
* Assume there is no residual value and the machinery is used for the entire year.
At the End of Year 1
- Carrying Amount 900,000 THB
- Tax Base 800,000 THB
Taxable temporary difference 100,000 THB
DTL 100,000 x 20% = 20,000 THB
Journal Entry
Dr. Income Tax Expense 20,000 THB
Cr. Deferred Tax liability 20,000 THB
Conclusion: Company B benefits from higher tax depreciation in the first year, resulting in lower current income tax. However, the company will face higher taxable income and tax payments in future periods as the temporary difference reverses.
Case Study: Asset Impairment with Different Accounting and Tax Depreciation Periods
This situation is commonly encountered in hotels, real estate businesses, and companies with significant investments in fixed assets.
Company C owns a hotel building with an original cost of THB 100 million.
Accounting Treatment:
Original cost = 100 MB
Useful life = 20 years
Annual depreciation = 5 MB
Tax Treatment :
Original cost = 100 MB
Useful life = 25 years
Annual depreciation = 4 MB
Assume that the company has owned and used the building for five years and that the 4% annual tax depreciation rate is permitted under the relevant tax regulations.
At the end of Year 5, the company determines that the building's Recoverable Amount is THB 50 million.
Therefore, the company must recognize an impairment loss under TAS 36 – Impairment of Assets.
Step 1: Calculate the Asset's Carrying Amount Before Impairment
Accounting basis:
Accumulated depreciation = 5 MB x 5 years = 25 MB
Carrying Amount before impairment = 100 − 25 = 75 MB
Tax basis:
Accumulated tax depreciation = 4 MB x 5 years = 20 MB
Tax Base before impairment = 100 − 20 = 80 MB
Therefore, before recognizing the impairment loss.
Step 2: Record the Impairment Loss
Dr. Impairment Loss 25 MB
Cr. Accumulated Impairment Loss 25 MB
Assume that the impairment loss is not deductible for tax purposes in the current year and does not change the building's Tax Base.
Step 3: Calculate the DTA After Impairment
Accounting Carrying Amount:
- Before impairment = 75 MB
- After impairment = 50 MB
Tax Base:
- Before impairment = 80 MB
- After impairment = 80 MB
The deductible temporary difference after impairment is 80 MB − 50 MB = 30 MB
DTA = 30 MB × 20% = 6 MB
Since the company has already recognized a DTA of 1 MB, it must recognize an additional DTA of 5 MB.
Dr. DTA 5 MB
Cr. Income Tax Expense 5 MB
Important: The calculated DTA of THB 6 million does not automatically qualify for full recognition. The company must assess whether sufficient future taxable profits will be available to utilize the deductible temporary difference.
Step 4: How Should Depreciation Be Calculated in the Following Year?
Assume that:
The building continues to be used.
The remaining useful life remains unchanged.
There is no residual value.
No additional impairment loss or impairment reversal occurs.
Accounting depreciation:
Carrying Amount after impairment = 50 MB
Remaining useful life = 15 years
Annual depreciation: = 50 ÷ 15 = 3.333 MB
Tax depreciation:
The company continues to claim tax depreciation of THB 4 million per year based on the original tax depreciation schedule.
At the End of Year 6
Carrying Amount = 46.667 MB
Tax Base = 76 MB
Deductible temporary difference = 29.333 MB
DTA at the end of Year 6 29.333 x 20% = 5.867 MB
Compared with the DTA of THB 6 million at the end of Year 5, the DTA decreases by approximately THB 0.133 million.
Journal Entry
Dr. Income Tax Expense 0.133 MB
Cr. DTA 0.133 MB
Why Does the DTA Decrease?
After recognizing the impairment loss, annual accounting depreciation decreases to approximately THB 3.333 million, while tax depreciation remains at THB 4 million per year.
As a result, the temporary difference between the accounting Carrying Amount and the Tax Base gradually decreases.
This example assumes that the company continues to meet the criteria for recognizing the full DTA in every reporting period.
Key Considerations When Calculating DTA and DTL
1. Not All Accounting and Tax Differences Result in DTA or DTL
It is important to distinguish between Temporary Differences and Permanent Differences.
For example, tax penalties that are permanently non-deductible do not create a Deferred Tax Asset.
2. Recognizing an Impairment Loss Does Not Automatically Create a Recognizable DTA
A company must assess whether the temporary difference will result in future tax deductions and whether sufficient future taxable profits are expected to be available.
3. Always Calculate Deferred Tax Based on the Carrying Amount and Tax Base
Companies should not consider only the impairment expense recognized in the current year.
Previous differences in accumulated accounting and tax depreciation may already have created temporary differences that must be included in the calculation.
4. Review Deferred Tax Assets at Every Reporting Date
Companies must reassess the recoverability of recognized Deferred Tax Assets at the end of each reporting period.
If sufficient future taxable profits are no longer expected to be available, the carrying amount of the DTA may need to be reduced.
5. Consider How Temporary Differences Will Reverse in the Future
โThis is particularly important for assets that may be sold, disposed of, or demolished before the end of their estimated useful lives.
Such events may affect the Carrying Amount, Tax Base, and timing of the reversal of temporary differences.
Conclusion:
Deferred Tax Assets and Deferred Tax Liabilities are not simply about paying more or less income tax in the current year.
Instead, they reflect the future tax consequences of temporary differences between accounting and tax treatments.
Key Takeaways!
DTA = Future Tax Benefit
DTL = Future Tax Obligation
Deferred tax is calculated based on temporary differences between the Carrying Amount and Tax Base of assets and liabilities.
Recognition must comply with the requirements of TAS 12 – Income Taxes.
For businesses with substantial fixed assets, regularly preparing a reconciliation schedule between accounting Carrying Amounts and Tax Bases can help ensure that deferred tax calculations are accurate, transparent, and easier to verify.
This article is general information, not advice for a specific case. Please consult us before making a decision.